
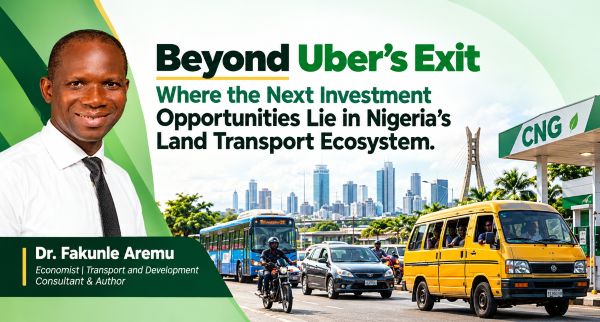
If Nigeria’s mobility demand remains strong but traditional operating models are under pressure, the next question for concern by the investors is well predicted
Where is the investable opportunity?
The answer may not lie in another ride-hailing application alone.
Nigeria’s land transportation ecosystem presents opportunities across the mobility value chain, particularly in vehicle financing and leasing, CNG infrastructure, electric mobility, fleet management, mass transit, digitalisation of informal transport and supporting services. Some of the hidden investment opportunities in the value chain are:
1. Investment Opportunity One is Vehicle Financing and Leasing. This implies financing the asset behind the trip
Every transport service ultimately requires an asset.
Whether the operator drives for Bolt or inDrive, runs a private pick-and-drop service, operates a keke NAPEP or manages staff buses, somebody must finance the vehicle.
That creates an important investment opportunity.
Commercial vehicles can potentially be financed through lease-to-own, hire-purchase, revenue-based financing and fleet-leasing models, particularly where technology allows financiers to monitor vehicle location, utilisation and repayment performance.
Rather than lending to drivers purely on conventional collateral, financiers could increasingly underwrite the cash-generating capacity of the vehicle.
A well-designed mobility-finance platform could combine vehicle acquisition, insurance, telematics, maintenance, repayment collection and driver verification within one system.
This creates opportunities for commercial banks, microfinance institutions, leasing companies, fintechs, OEMs and development finance institutions.
But the model carries significant risks, some of which include Expensive Capital and Weak Access to Vehicle Finance
Nigeria’s high financing costs make commercial vehicle acquisition difficult. Long repayment periods also expose lenders to inflation, depreciation, default and vehicle-recovery risks.
A driver purchasing a vehicle through expensive informal financing may spend a substantial proportion of daily earnings servicing the asset before paying for fuel, maintenance and household expenses.
However, here are recommended solutions to this risk.
- Build cash-flow-based mobility financing.
Financiers should use verified trip revenue, digital payments, GPS data and vehicle utilisation records to supplement conventional credit assessment. This could make financing accessible to commercially viable drivers who lack traditional collateral.
- Create blended-finance facilities for commercial mobility.
Development finance institutions, governments and impact investors can provide guarantees, first-loss capital or concessional funding while private financiers provide commercial capital. This could reduce financing costs without requiring the government to own transport businesses.
- Finance fleets rather than isolated vehicles.
Aggregated fleets are easier to monitor, insure and maintain than thousands of independently financed vehicles. Fleet financing also creates economies of scale in vehicle procurement, maintenance, insurance and fuel or energy purchasing.
For investors, therefore, transportation finance should increasingly be viewed as an asset-backed infrastructure business rather than ordinary consumer lending.
2. Investment Opportunity Two is CNG: Nigeria’s Most Immediate Alternative-Fuel Opportunity
One of the most significant structural changes occurring within Nigerian transportation is the expansion of Compressed Natural Gas (CNG).
The economics are compelling because Nigeria has substantial domestic gas resources while petrol-based transportation has become considerably more expensive following subsidy reform.
By 2026, the Federal Government’s Presidential Initiative on Compressed Natural Gas and Electric Vehicles reported more than 120,000 vehicle conversions, over 400 certified conversion centres, more than 90 CNG refuelling stations and over 7,700 trained technicians (Pi-CNG & EV, 2026).
The initiative reports that CNG can be approximately 40% to 60% cheaper per kilometre than petrol, although actual savings depend on location, vehicle type, fuel prices, conversion quality and access to refuelling infrastructure (Pi-CNG & EV, 2026).
Infrastructure investment is also accelerating.
In May 2026, four MDGIF-supported CNG projects were commissioned across Lagos, Abuja and Owerri. One of these, the Portland Gas Mother Station at Ojota, Lagos, has a stated dispensing capacity of 96,000 standard cubic metres per day alongside associated storage and distribution infrastructure (State House, 2026).
This creates several potential businesses:
CNG conversion centres; gas distribution; mother and daughter stations; mobile refuelling; fleet conversion; cylinder and conversion-kit distribution; vehicle maintenance; technician training; safety inspection and CNG-powered mass transit.
For investors considering Nigeria’s mobility transition, CNG is therefore becoming difficult to ignore.
However, scale remains the challenge as Alternative-Fuel Infrastructure Is Still Uneven!
Nigeria’s transport fleet is enormous and geographically dispersed. Even with rapid growth in CNG infrastructure, the official network listed about 91 refuelling stations across 23 states in 2026 (Pi-CNG & EV, 2026).
This means a vehicle may be technically capable of operating on CNG but commercially constrained if reliable refuelling is unavailable along its operating corridor.
That creates a classic infrastructure problem: operators hesitate to convert without stations while investors hesitate to build stations without sufficient vehicle demand.
To address this constraint, here are recommended solutions
- Develop transport corridors rather than scatter infrastructure.
CNG investment should initially concentrate on high-volume routes such as Lagos-Ibadan, Abuja-Kaduna-Kano and major intra-city transport corridors. As well as the key routes across the South-East, South-South, North-East and North-Central. This implies concentrating vehicles and refuelling infrastructure along the active routes to improve station utilisation and reduce investor risk.
- Anchor stations around captive fleets.
Investors should prioritise depots serving buses, logistics companies, staff transportation, government fleets and large ride-hailing fleets. A station backed by predictable daily consumption is more bankable than one dependent entirely on walk-in customers.
- Use public-private infrastructure financing.
Government should focus on standards, enabling infrastructure, incentives and risk reduction while private investors finance commercially viable conversion and refuelling businesses.
The expansion of the Pi-CNG mandate in March 2026 also introduced a stronger financing dimension, with the government directing collaboration with CreditCorp, financial institutions and other partners to develop affordable conversion financing (State House/Pi-CNG & EV, 2026).
This could eventually create an entire transport-energy investment class around Nigerian mobility.
3. Investment Opportunity Three: Electric Mobility and the Importance of Starting Where the Economics Work
Electric vehicles are another important opportunity, but Nigeria should resist over-dependence on copying EV transition models which are designed for countries with stronger electricity systems and higher household incomes.
Nigeria’s national electricity constraints remain material. Reuters reported in August 2026 that the national grid supplies only around 4,000 MW for a population exceeding 200 million, while public EV charging infrastructure remains limited. The report cited about 48 public charging stations by late 2025 (Reuters, 2026).
This does not mean EVs have no future in Nigeria.
It means investors must identify where electrification already makes economic sense.
The strongest early opportunities may be electric motorcycles, tricycles, delivery vehicles, buses and predictable-route commercial fleets.
These vehicles typically travel frequently, making fuel savings more valuable and allowing charging or battery swapping to be concentrated around depots and operating zones.
The Nigerian policy environment is also becoming more supportive. In March 2026, the Federal Government expanded the Presidential CNG Initiative into the Presidential Initiative on CNG and Electric Vehicles, giving it responsibility for coordinating EV deployment, charging infrastructure and related investment (Pi-CNG & EV, 2026).
Nigeria has also introduced fiscal incentives. Under the 2026 fiscal measures, full import-duty exemptions were announced for electric vehicles and mass-transit buses (Reuters, 2026).
However, the challenges to resolve are obvious: Electricity Reliability and EV Charging Infrastructure
An electric transport system cannot scale sustainably if charging depends on an unreliable grid supplemented by diesel generators. That would weaken both the economics and environmental rationale for electrification.
Here are three recommended solutions for investors that are ready to scale:
- Prioritise commercial two- and three-wheelers.
Electric motorcycles and tricycles can have smaller battery requirements and predictable operating patterns. Battery swapping can also reduce charging downtime.
- Build solar-supported charging hubs.
Charging infrastructure can be integrated with solar PV, batteries and grid supply. This reduces dependence on unreliable grid electricity while creating opportunities for distributed-energy investors.
ALSO READ Beyond Uber’s exit, by Dr. Fakunle Aremu [I]
- Develop battery-as-a-service models.
Separating battery ownership from vehicle ownership can lower the upfront purchase price. Operators could pay for energy or battery usage while specialist companies own, maintain and replace the batteries.
Nigeria is already seeing private-sector experimentation with battery-swapping infrastructure while local assembly of electric vans and minibuses is emerging. Some African commercial EV models are also using lease-to-own and pay-as-you-drive structures to reduce upfront costs (Reuters, 2026; Associated Press, 2026).
4. Investment Opportunity Four: The Bigger Digital Opportunity May Be the Danfo, Keke and Informal Fleet
Nigeria does not necessarily need to eliminate informal transportation.
It needs to make it safer, more efficient, more accountable and more investable.
Consider what could happen if a large network of danfo or keke operators were connected to a digital operating platform which provides real-time:
digital fare collection, GPS tracking, passenger information, route data, vehicle maintenance records, insurance, driver identification, credit scoring and fleet financing.
Suddenly, an informal operator will begin to generate structured economic data.
That data itself has value.
Banks can finance vehicles more intelligently. Insurers can price risk better. Governments can understand passenger flows. Fleet owners can monitor vehicles. Passengers gain greater visibility and safety.
The opportunity is therefore larger than another passenger-booking app.
Nigeria needs a digital operating layer for informal mobility.
However, the investor needs to address fragmentation and Informality
This is because the informal transport system consists of numerous independent owners, drivers, associations, unions and local operating structures; while fragmentation makes standardisation, investment and technology adoption difficult.
Here are recommended ways out:
- Organise operators into digitally enabled fleet cooperatives.
Operators can retain ownership while sharing technology, insurance, maintenance, financing and payment infrastructure.
- Introduce interoperable mobility payments.
Passengers should increasingly be able to pay across buses, BRT, keke and other organised transport services through cards, mobile wallets, QR codes or account-based systems.
- Use incentives rather than prohibition to formalise operators.
Access to cheaper vehicle finance, insurance, CNG conversion, designated terminals and maintenance programmes can be conditional on registration, safety compliance and digital record keeping.
With these, formalisation then becomes commercially attractive rather than merely regulatory.
Nigeria’s Mobility Opportunity Is Becoming an Infrastructure Story
This leads to an important conclusion for investors.
- The next major Nigerian mobility company may not necessarily be another Uber.
- It could be the company that finances 20,000 commercial vehicles.
- It could be the company operating CNG stations along major transport corridors.
- It could be a battery-swapping network serving thousands of electric motorcycles.
- It could be a technology company digitising danfo payments and operations.
- It could be a fleet operator providing staff transportation to corporations.
Or it could be an integrated mobility company combining vehicles, financing, energy, technology and transport operations.
That is why Uber’s departure should not be interpreted simply as evidence that Nigerian transportation is unattractive.
It should encourage a more sophisticated question:
Which parts of Nigeria’s mobility value chain can generate sustainable returns despite the country’s operating constraints?
That is where the investment conversation should now move.
Dr. Fakunle Aremu is a Nigerian economist, management consultant and trade and investment expert with experience in private-sector development, policy advisory, market systems and investment facilitation. He holds a PhD in Agricultural Economics and serves as Nigeria Country Director of the U.S.-Africa Trade Commission and the Managing Director of Cedro Royal Multiventures Limited. His work focuses on identifying commercially viable opportunities across trade, infrastructure, clean energy, agribusiness and emerging investment ecosystems. He works with businesses, investors, governments and development institutions to translate market opportunities and economic challenges into practical strategies for sustainable investment and development in Nigeria and Africa.
